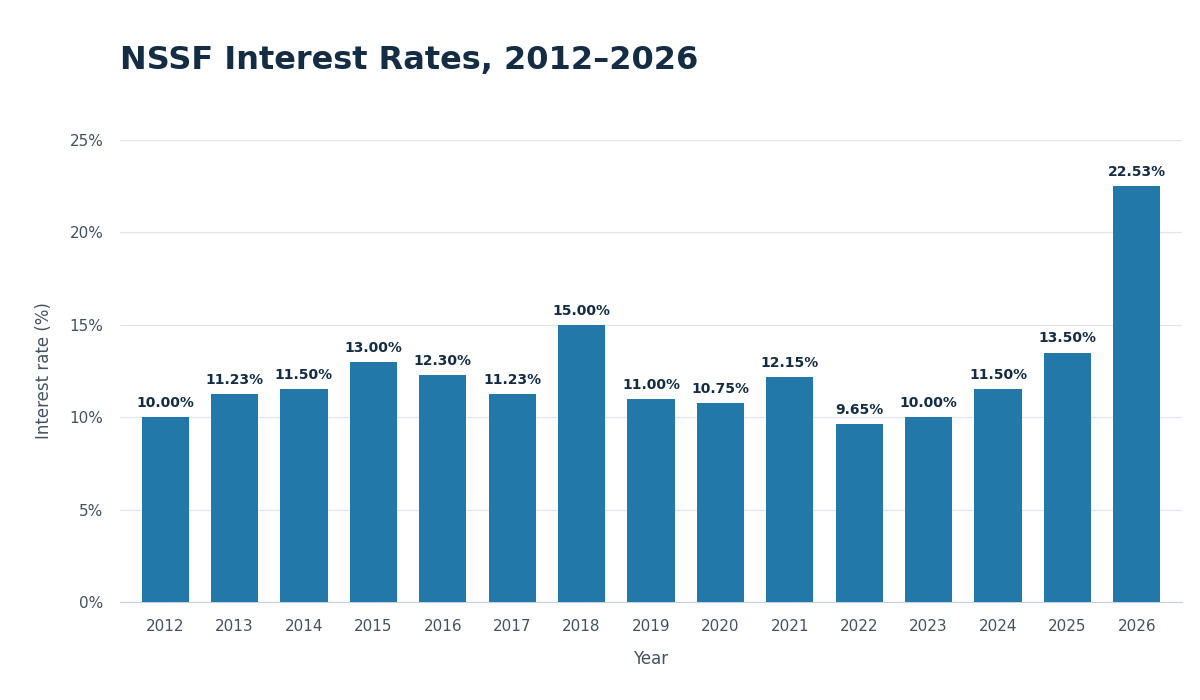
The National Social Security Fund (NSSF) on September 24th, declared a historic interest rate of 22.53% for the financial year 2025/2026, the highest in the Fund’s 40-year history, triggering wild celebrations at the 14th Annual Members Meeting.
The announcement, made by the Minister of Finance, Planning and Economic Development, Hon. Henry Musasizi, means that a total of UGX 5.44 trillion will be shared among NSSF’s 3.5 million members. This is UGX 2.64 trillion more than the UGX 2.78 trillion shared the year before. The rate is well above the 10-year average inflation of 4.1% and the 2025/2026 inflation of 3.7%.
The declaration capped a day of detailed presentations, candid reflections, and pointed challenges, all converging on the conviction that NSSF is performing well, but it must do more to drive Uganda’s national development agenda.
NSSF Managing Director Patrick Ayota painted a largely positive picture of the fund, describing 2025/26 as a year of strong growth and strategic progress. He reported that the Fund’s assets grew by 26.4%, from UGX 26 trillion to UGX 32.87 trillion, while member funds grew from UGX 25.55 trillion to UGX 31.85 trillion. Growth was driven by robust investment income and continued positive net contributions. He assured members that NSSF is a fully funded scheme, able to meet all its obligations to members.
“The member remains at the centre of everything the Fund does. If the fund closed today, it would take us about 90 days to pay 80% of our members,” Ayota said. “We have that money in bonds; we can sell them. It may take us the rest of the year to sell off the MTN shares and the real estate, but all members would be paid fully,” Ayota said.
He also highlighted the Fund’s value creation, noting that for every shilling spent, NSSF created UGX 27 in value, compared to about UGX 17 in Kenya and UGX 13–15 in Tanzania.
Chairman of the NSSF Board of Directors, Dr. David Ogong, echoed Ayota’s optimism, praising the Board, management, and staff for what he called a stunning performance. He noted that the Fund had grown by UGX 6.8 trillion in one year and by over UGX 10 trillion in two years. “So, members, your funds are safe,” Ogong said and thanked the Ministry of Gender, Labour and Social Development, and the Ministry of Finance for their oversight and support.
The Minister of Gender, Labour and Social Development, Hon. Lt. Gen. Henry Tumukunde, struck a different tone. He challenged the NSSF Board and management to embrace competition, allow for exits, and stop treating the Fund as a place of permanent stay.
Tumukunde urged NSSF to see itself not merely as a custodian of savings but as a catalyst for Uganda’s economic transformation. He cited Zambia as an example of a country where pension funds are felt in the economy. He called for a fundamental shift in mindset, saying the Fund must reflect on the economy and be deployed maximally for the good of the nation.
Minister of Finance, Planning and Economic Development Henry Musasizi acknowledged the need to balance protecting members’ savings and leveraging pension funds to finance national development. He referenced the government’s tenfold growth strategy, which aims to grow Uganda’s economy to $500 billion by 2040, and said pension funds would play a critical role in closing the savings-investment gap.
“The mobilization of domestic long-term capital by the NSSF can play a catalyst role in financing national priorities and accelerating inclusive economic growth,” Musasizi said. “At the same time, NSSF members expect their savings to be preserved, protected, and invested to generate competitive, risk-adjusted returns over the long term.”
He said the two objectives were not mutually exclusive and pledged that the Ministry of Finance would continue to support the Fund in maintaining the appropriate balance. He also promised to work closely with the Minister of Labour and the Board to expedite investment decisions where opportunities are time-sensitive.
The question-and-answer session that followed generated a wide range of member concerns, including mid-term access, employer non-remittance, and the possibility of taking loans from the fund. On mid-term access, MD Patrick Ayota explained that the NSSF Act, 2022 requires 45 years of age and 10 years of savings, which translates to 120 monthly entries. He encouraged members to engage their Members of Parliament if they wanted the law amended.
On employers who default, the Chief Commercial Officer Geoffrey Sajjabi urged members to whistle-blow if deductions are not remitted. Chief Legal Officer Agnes Isharaza said the Fund has a litigation and enforcement team and would pursue employers in court if need be.
On loans, Ayota was unequivocal saying, “the law as written does not allow us to give any person a loan. If there’s something you need the law to change, please talk to your Member of Parliament.”
From their different perspectives, all speakers shared the conviction that NSSF can do more for members and for the nation. From Ayota’s call for members to believe in Uganda, Tumukunde’s demand for competition and economic impact, to Musasizi’s vision of pension funds as a driver of national development, NSSF’s record performance is a foundation for better performance, not a final destination.
Speaking on Sustainability and Long-Term Investment, Capital Markets Authority CEO Ms. Josephine Okui Ossiya noted that Uganda’s retirement savings have grown to approximately UGX 36 trillion, covering about four million scheme members. However, she emphasised that expanding coverage to informal workers and SMEs must remain a priority. She called for stronger public-private partnerships and greater innovation in investment products, including infrastructure bonds, to create more opportunities for deploying growing retirement savings.
Flexibility also emerged as a critical requirement for expanding coverage. Ms. Ossiya argued that contribution mechanisms should reflect the irregular income patterns of many Ugandans, allowing them to save as and when they earn. She further highlighted insurance as an important component of retirement security, particularly through affordable life, disability and income protection products that can shield households from financial shocks.
UIA CEO Mr. Jonan Kisakye reinforced the importance of collaboration, innovation and public trust. He noted that expanding pension coverage requires accessible information, strategic partnerships and solutions that respond to the realities of Uganda’s workforce. He also emphasised the need to improve public understanding of the role of insurance within the retirement ecosystem.
The challenge of inclusion was further underscored by Mr. Kirya Hassan Alimansi, Chairman of Finance, Planning and Investment at the Informal Workers Social Protection Scheme. He observed that approximately 80% of workers are in the informal sector and remain largely unprotected because conventional pension and insurance products were not designed around their income patterns and risks. He called for affordable, flexible micro-pension and micro-insurance solutions supported by partnerships among government, regulators, insurers, technology providers and workers’ organisations.
From the regulatory perspective, Daisy Lynda Nabakooza, URBRA’s Chief Manager of Supervision and Market Conduct, stressed that pension planning is not solely an informal-sector issue. With savings remaining low and people living longer in retirement, she urged Ugandans to begin preparing early. Adding that Under URBRA’s current five-year plan, Uganda aims to increase informal-sector pension inclusion to 20 percent, from less than one percent. Framing meaningful inclusion around three principles: accessibility, affordability and quality at scale.
Similarly, Mr. Patrick Kimathi, CEO of Old Mutual Uganda, called for micro-pension products that allow informal workers to contribute daily, weekly or monthly according to their incomes. Mr. Andrew Mwangi Ngumo of Zamara emphasised that pension reform must focus on people rather than merely assets under management, advocating for digitisation and individual-centred retirement solutions.
The Chief Guest, Mr. Bua Victor Leku of the Ministry of Public Service, highlighted the need to prepare for Uganda’s growing population and future elderly population, while noting the Government’s step in the right direction of introducing a funded, contributory defined-benefit scheme for public servants.
Closing the discussions, URBRA CEO Mr. Martin Anthony Nsubuga emphasised that no single institution can achieve pension inclusion alone. He called for deliberate collaboration between the pension, insurance and banking and telecom sectors, with technology playing a central role in making retirement saving more accessible.
The key message from the UIA Forum was clear, Uganda’s pension future will depend not only on growing savings, but on making those savings accessible, flexible, protected and meaningful to every Ugandan.